
50 Dollar Bill Rumor False: What’s Really Going On and What to Do

50 dollar bill rumor false is a phrase that pops up whenever social media claims that $50 bills are being “discontinued,” “no longer accepted,” or “worthless” at banks and stores.
Contents
27 sections
-
Why the "$50 bill" rumor keeps coming back
-
Common versions of the rumor
-
50 dollar bill rumor false: what's true vs what's not
-
Why businesses sometimes refuse $50 bills
-
How U.S. currency validity works (in plain English)
-
Quick authenticity checks for a $50 bill
-
1) Feel the paper and printing
-
2) Look for security features (varies by series)
-
3) Watch for red flags that often show up on counterfeits
-
What to do if you think you received a counterfeit $50
-
Step-by-step checklist
-
What not to do
-
Cash-handling decision rules (by timeline)
-
Under 1 year: prioritize liquidity and low risk
-
1 to 3 years: build a buffer and reduce cash exposure
-
3 to 7 years: focus on stability and planned goals
-
7+ years: long-term planning
-
Real-number scenarios: what this looks like with $50 bills
-
Scenario 1: You keep a small cash cushion at home (total $200)
-
Scenario 2: You are paid partly in cash (weekly cash income $350)
-
Scenario 3: You got one suspicious $50 and you are on a tight budget (monthly surplus $120)
-
Comparison: ways to reduce counterfeit risk (with named examples)
-
Practical rule for choosing an option
-
Counterfeit and cash scams that can look like "$50 bill news"
-
What banks and regulators can help with
-
Quick checklist: reduce your risk with $50 bills
-
Bottom line
In most cases, these posts mix a small truth with a big misunderstanding. The reality is simpler: the U.S. government does not suddenly cancel a common bill because of a viral post. What does happen is that counterfeit warnings circulate, some businesses tighten cash-handling rules, and older bill designs can confuse people who do not handle cash often.
This guide breaks down the most common $50 bill rumors, what is actually true, how U.S. currency stays valid over time, and practical steps to protect yourself from counterfeit losses and cash-related scams. You will also see real-number examples for handling a suspicious $50 bill without wrecking your budget.
Why the “$50 bill” rumor keeps coming back
Rumors about the $50 bill often follow the same pattern:
- A post claims “banks won’t take $50s” or “stores are refusing $50 bills.”
- Someone shares a photo of an older design or a damaged bill.
- A local business changes its policy due to counterfeiting or cash theft.
- The story spreads nationwide as if it is an official rule.
What is usually happening is not a change in legal tender status. It is a mix of private business policies, counterfeit concerns, and confusion about older series notes.
Common versions of the rumor
- “The government is discontinuing $50 bills.” People confuse redesigns and anti-counterfeit updates with discontinuation.
- “Banks won’t accept $50 bills anymore.” Banks may scrutinize large bills more closely, but that is not the same as refusing legitimate currency.
- “Old $50 bills are invalid.” Older designs are generally still spendable if they are genuine and not excessively damaged.
- “Stores are banning $50s.” Some stores choose not to accept large bills to reduce counterfeit risk or because they do not keep enough change.
50 dollar bill rumor false: what’s true vs what’s not
Let’s separate the practical truth from the viral claims.
| Claim you might see | Reality | What to do |
|---|---|---|
| “$50 bills are being discontinued.” | U.S. currency denominations are not discontinued by rumor. Design updates happen, but that does not automatically invalidate older notes. | Use normal caution. If a business refuses a bill, ask for another payment method or use a bank deposit. |
| “Banks won’t take $50 bills.” | Banks typically accept genuine U.S. currency. They may verify authenticity or reject suspected counterfeits. | Deposit at your bank and request a receipt. If the bill is questioned, ask about the bank’s process. |
| “Old $50 bills are invalid.” | Older series notes are commonly still valid if genuine. Confusion happens because security features differ by series. | Learn basic authenticity checks for the series you have. |
| “Stores are refusing $50s everywhere.” | Some stores refuse large bills based on their own policy, cash drawer limits, or counterfeit incidents. | Carry a backup payment option. Break large bills at a bank when possible. |
| “If you get a fake $50, you can just get reimbursed.” | Counterfeit losses are often not reimbursed. If you pass a counterfeit bill, you can create legal trouble for yourself. | Do not spend it. Bring it to your bank or local law enforcement for guidance. |
Why businesses sometimes refuse $50 bills
Even when the rumor is false, you may still run into a “no $50s” sign. Common reasons include:
- Change-making limits: A small store may not have enough $10s and $5s to break a $50 early in the day.
- Counterfeit risk: Some counterfeiters target $50s because they are less scrutinized than $100s but still valuable.
- Employee training: Cashiers may not know what to look for on older series notes.
- Loss prevention: Some businesses reduce cash acceptance to lower robbery risk.
How U.S. currency validity works (in plain English)
In the U.S., you will often hear the phrase “legal tender.” In everyday life, what matters is:
- Genuine bills are generally spendable even if they are older designs.
- Private businesses can set payment policies such as “card only,” “no bills over $20,” or “exact change.”
- Banks can reject suspected counterfeit and may keep it for investigation.
If you want to understand how to handle suspicious money and common scam tactics, the FTC has practical guidance on reporting fraud and avoiding scams: https://consumer.ftc.gov/.
Quick authenticity checks for a $50 bill
You do not need special equipment to do basic checks. Use a few steps together rather than relying on only one test.
1) Feel the paper and printing
- Genuine U.S. currency paper has a distinct feel, not like standard printer paper.
- Many genuine notes have raised printing you can feel with a fingernail, especially on the portrait and text.
2) Look for security features (varies by series)
Security features differ depending on the year series. On many modern notes, you may find:
- Watermark: A faint image visible when held to light.
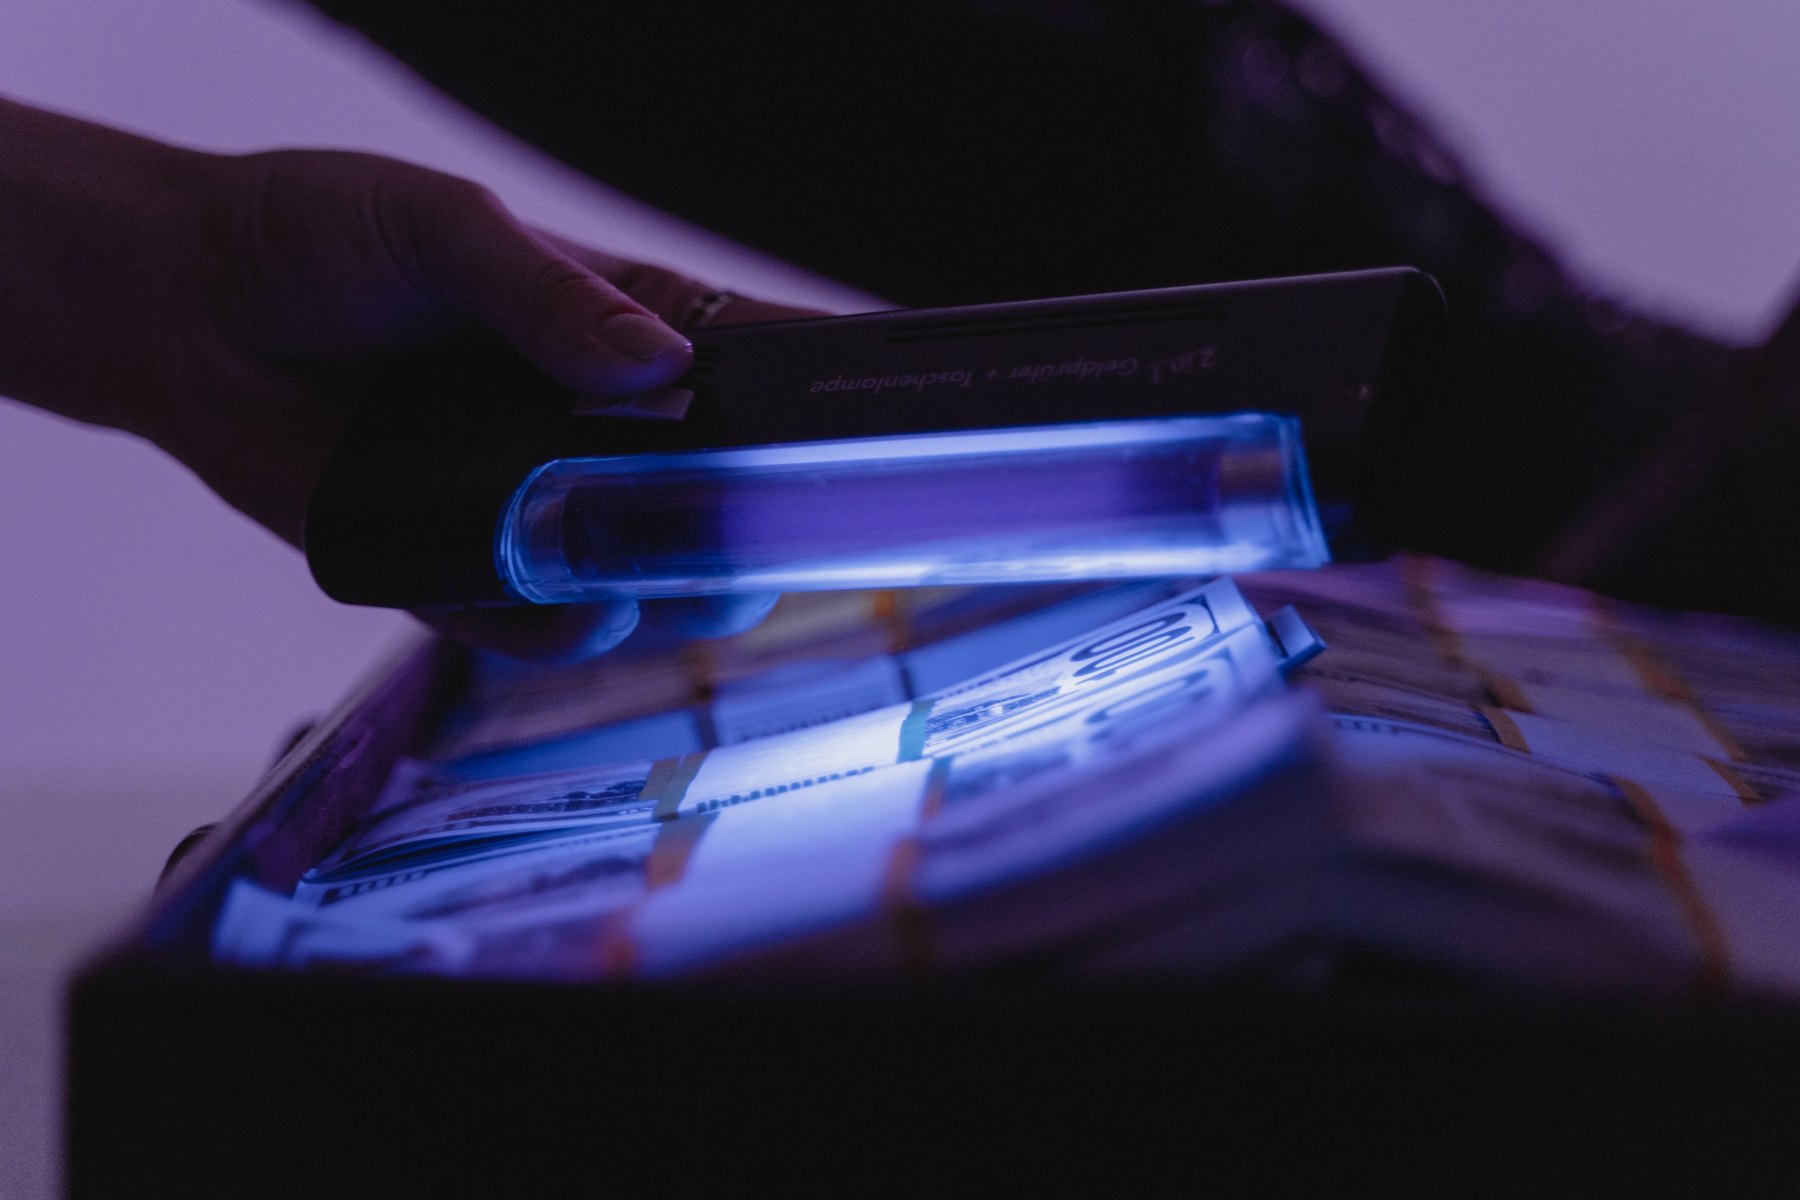
- Security thread: A strip embedded in the paper that may glow under UV light.
- Color-shifting ink: Ink that changes color when you tilt the bill.
If you are unsure which features your bill should have, compare it to another $50 from a trusted source, or ask your bank teller to verify it.
3) Watch for red flags that often show up on counterfeits
- Blurry borders or fuzzy microprinting
- Ink that smears easily
- Wrong color tones or odd shine
- Repeated serial numbers across multiple bills
- Paper that feels waxy, overly smooth, or too stiff
What to do if you think you received a counterfeit $50
If you suspect a $50 bill is counterfeit, focus on two goals: avoid passing it to someone else, and document what happened while details are fresh.
Step-by-step checklist
- Do not spend it. Passing a counterfeit bill can create serious problems even if you did not mean to.
- Handle it as little as possible. Put it in an envelope to preserve condition.
- Write down details: date, time, location, who gave it to you, and any receipt or transaction info.
- Contact your bank. Ask how they handle suspected counterfeit notes and whether you should bring it in.
- Consider reporting: If you believe you were scammed, reporting helps authorities track patterns. The FTC is a starting point for many consumer fraud reports: https://consumer.ftc.gov/.
What not to do
- Do not try to “test” it by spending it at a different store.
- Do not post identifying details online that could escalate conflict with a business or person.
- Do not assume you will be reimbursed. Plan for the possibility that the money is a loss.
Cash-handling decision rules (by timeline)
Even though this topic is about a rumor, it connects to a real money decision: how much cash you keep, how you store it, and how you reduce the chance of getting stuck with suspicious bills.
Under 1 year: prioritize liquidity and low risk
- Use a checking account for bills and daily spending.
- Keep a small amount of physical cash for emergencies, but not so much that a loss would strain your budget.
- If you regularly receive cash (tips, side gigs), deposit frequently to reduce the chance of holding a counterfeit note.
1 to 3 years: build a buffer and reduce cash exposure
- Increase your emergency fund toward 3 to 6 months of essential expenses.
- Shift more transactions to traceable methods when possible (bank transfers, debit, credit) to reduce cash disputes.
3 to 7 years: focus on stability and planned goals
- For planned purchases, keep funds in accounts that match your risk tolerance and timeline.
- Use cash mainly for convenience, not storage.
7+ years: long-term planning
- Long-term goals typically benefit from a plan that balances growth and risk. Physical cash is usually not a long-term strategy because it can be lost, stolen, or slowly eroded by inflation.
Real-number scenarios: what this looks like with $50 bills
Below are three practical scenarios that show how to handle cash and reduce the impact if you ever get stuck with a suspicious bill. These are examples, not one-size-fits-all plans.
Scenario 1: You keep a small cash cushion at home (total $200)
Goal: Have emergency cash but limit loss risk.
- $60 in $10 bills
- $80 in $20 bills
- $40 in $5 bills
- $20 in $1 bills
Total: $200
Decision rule: If you receive a $50 bill, consider exchanging it at your bank for smaller denominations rather than keeping it in your home cash stash.
Scenario 2: You are paid partly in cash (weekly cash income $350)
Goal: Reduce counterfeit risk and improve tracking.
- $250 deposited to your bank within 1 to 2 days
- $75 kept for weekly variable spending (gas, groceries top-ups)
- $25 kept as small bills for tips and transit
Total: $350
Decision rule: If you receive any large bills ($50 or $100), deposit them rather than recirculating them. The faster you deposit, the less likely you are to forget where a questionable bill came from.
Scenario 3: You got one suspicious $50 and you are on a tight budget (monthly surplus $120)
Goal: Avoid a spiral if the $50 turns out to be a loss.
- $50 set aside temporarily (do not spend) while you verify it at your bank
- $40 kept for groceries buffer
- $30 added to a small emergency fund
Total: $120
Decision rule: Until the bill is verified, treat it as unavailable money. If your budget is tight, plan spending as if you do not have that $50.
Comparison: ways to reduce counterfeit risk (with named examples)
You cannot eliminate risk completely, but you can reduce it by changing how you accept and store money. Here are recognizable options people use, with what to compare and the main drawback to watch for.
| Option | Best fit | What to compare | Main drawback |
|---|---|---|---|
| Deposit cash at a bank branch (Bank of America, Chase, Wells Fargo, Citi) | People who receive cash often and want quick verification | Branch access, deposit holds, cash handling policies | Time and travel, and suspected counterfeit may be retained |
| Use an ATM cash deposit (your bank’s ATM network) | After-hours deposits and routine cash income | Deposit limits, posting time, error resolution process | If there is a dispute, resolution can take time |
| Retail cash services (Walmart MoneyCenter) | People who already shop there and need basic cash services | Current fees, service availability, limits | Fees can apply, and not all services are available everywhere |
| Peer-to-peer payments (PayPal, Venmo, Cash App, Zelle) | Splitting bills and reducing cash exchange with friends | Transfer speed, fees for instant transfer, fraud protections, dispute options | Scams and payment reversals can happen depending on method and settings |
| Card payments instead of cash (Visa, Mastercard, American Express) | Everyday purchases where merchants accept cards | Rewards vs interest costs, fees, budgeting impact | Overspending risk and interest if you carry a balance |
Practical rule for choosing an option
- If you receive cash weekly or more, prioritize fast deposit and receipts.
- If you rarely use cash, prioritize smaller denominations and a backup payment method.
- If you run a small business, consider training, clear policies, and tools like counterfeit detection pens or UV lights, but do not rely on only one method.
Counterfeit and cash scams that can look like “$50 bill news”
Some scams use the rumor itself to pressure you into bad decisions. Watch for these patterns:
- Urgency: “Spend your $50s today or they will be worthless tomorrow.”
- Switch scams: Someone hands you a bill, distracts you, then claims you gave them a different denomination back.
- Marketplace scams: In-person sales where the buyer pays with a counterfeit $50 and disappears.
If you are dealing with fraud or identity theft concerns at the same time, it can help to monitor your credit reports. You can get free weekly reports (availability can change) at https://www.annualcreditreport.com/.
What banks and regulators can help with
If you are trying to understand your rights around deposits, disputes, and financial products, the CFPB has consumer resources and complaint options: https://www.consumerfinance.gov/.
If your concern is more basic, like whether your money is protected in a bank account, the FDIC explains deposit insurance coverage and how it works: https://www.fdic.gov/.
Quick checklist: reduce your risk with $50 bills
| Situation | Do this | Avoid this |
|---|---|---|
| You receive a $50 in a private sale | Meet in a well-lit public place, check the bill, consider digital payment | Rushing the exchange or accepting cash in poor lighting |
| You get a $50 as change | Check it before leaving the counter | Waiting until later when you cannot trace the transaction |
| You handle cash tips | Deposit frequently and keep notes of shifts and totals | Holding large amounts of cash for weeks |
| A store refuses your $50 | Use another payment method or exchange at your bank | Arguing about “legal tender” instead of solving the payment |
| You suspect a counterfeit | Stop using it, document details, contact your bank | Trying to pass it to someone else |
Bottom line
The “$50 bill is being discontinued” storyline is usually misinformation. The more practical issue is that counterfeits exist and some businesses limit large bills. If you handle cash often, build habits that reduce risk: check bills at the point of exchange, deposit cash regularly, keep receipts, and use traceable payments when it makes sense. If you ever end up with a suspicious $50, treat it as a verification problem, not spending money, until you confirm it is genuine.


